You’ll make this decision once.
Photograph 1 of 3: The harbour at 6:10 a.m.
Harbourline is an independent, flat-fee fiduciary practice in Boston: five advisors, $410M advised. We plan retirement transitions and equity compensation for people who built careers in tech and biotech, for a fee agreed before we start.
Six decisions we plan, on one fee.
Most households need three or four of these. The annual fee is set by the plan’s complexity before we start, and it stays the same whether the plan covers two of them or all six.
Retirement transition
The date work becomes optional, and the withdrawal order that pays for it: which account funds which year, in what sequence.
Equity compensation
Grants, exercise windows, and a sale schedule written down in advance, so a bad month never becomes a decision.
Tax strategy
Roth conversions, capital-gain harvesting and charitable timing, coordinated with your CPA in writing before the year closes.
Estate and family
Current documents and correct beneficiaries, kept in a binder your spouse has read and can find.
Education funding
Tuition planned to the semester, without quietly borrowing it from the thirty years that come after work stops.
Business exit
Valuation, structure, and the question nobody asks first: what the money has to do for you once the company is gone.
Most calls come in the week an offer, a grant or a retirement date lands on the table.
At 58: The package on the table
You’re 58. Nineteen years at the same company, and on Tuesday they offered you a package that expires at the end of the month. Pension or lump sum. Health coverage to 65, or a gap. A 401(k) allocation untouched since 2016. Four weeks to decide things that will shape thirty years.
We map the whole decision before you sign anything.
At 47: The net worth with one ticker on it
You’re 47. Eleven years vested. The RSUs kept coming, you never sold, and now one stock is 68 per cent of everything you own. Selling feels disloyal. Holding keeps you up at night. There is a defensible middle, and it has a schedule.
We build the selling plan you can live with, tax year by tax year.
Neither one exactly you? Tell us what is
A plan is drawn across thirty years.
Here is the shape of a typical Harbourline plan, for someone who is 55 today and wondering how much longer work is a requirement. Descend it, and the plan draws itself on the plate.
At 55: The map
Every account, grant, pension, and property in one drawing. We mark which options get exercised and in which tax years, what happens to the house, and the date work becomes optional rather than required.
Plate II · part i: The mapSpecimen
$2.61M held, in five accounts
Held
- 401(k), at work$1.24M
- Rollover IRA$610K
- Roth IRA$220K
- Brokerage, taxable$455K
- HSA$84K
Granted
- RSUs, four tranchesvest to 2031
- ISOs, 2019 grant42,000 sh
At 62: The paycheck, replaced
Salary stops. The withdrawal order starts: which account funds which year, sequenced so the tax bill stays quiet. Done well, retirement income is boring.
Plate II · part ii: The withdrawal orderSpecimen
- Brokerage, taxable$455K
- Rollover IRA$610K
- 401(k), at work$1.24M
- Roth IRA$220K
At 70: The floor
Delayed benefits switch on at their maximum, and the plan now rests on guaranteed income. The portfolio's job gets smaller, so market weather matters a little less every year.
Plate II · part iii: The floorSpecimen
Promised
- Pension, frozen$2,140 / mo
- Social Security, at 70$4,020 / mo
Floor, from 70$6,160 / mo
Beyond: The part your family will thank you for
Who inherits which account, which one pays the estate tax, and what happens to the house. Written where your family will find it, and walked through with them while you are still in the room.
Plate II · part iv: The part that outlives the planSpecimen
Owned
- The house, Belmont · beneficiary named$980K
- Mortgage, 2.75%−$210K
Work becomes optional2031
Reviewed every year. Redrawn when life changes.
The fee is flat. Here is all of it.
Priced by complexity, agreed before we start, billed quarterly. It does not rise with the market, and it never depends on what you buy, because you buy nothing here.
Foundation
One household, one employer's equity, a retirement inside ten years.
$9,600per year
Comprehensive
Multiple grants, a sale schedule, tax coordination with your CPA.
$15,000per year
Complex
Business equity, trusts, multi-state filings, family gifting.
$21,000per year
Every tier includes the annual redraw, unlimited meetings, the equity sale calendar, estate document review, and a direct line to your CPA. If your situation fits no tier, we quote a flat number in the first meeting and hold it for a year.
Fiduciary is a legal word for a plain arrangement: your interest comes first, and the promise is in writing.
You pay us. And nobody else does. No fund company, no insurer, no platform, no referral desk: our revenue is the fee on this gauge, in full.
We sell nothing. No in-house funds, no annuities in a drawer, no quota behind the advice. When we recommend an investment, we earn the same either way, which is nothing.
Flat means flat. At a percentage firm, advice to pay off the mortgage or gift to your kids shrinks the fee. Here it changes nothing, so you will actually hear it.
The plan we draw is the only thing we sell.
The arithmetic, at your balance.
Drop the sounding lead on your balance. The dashed course is what a 1% advisor bills that year; the level courses are our three fees. Where 1% costs less, the plate shows that too.
$2,400,000
$24,000
$15,000
At $2,400,000, 1% bills $24,000 this year. After a 10% fall it bills $21,600; after a 10% rise, $26,400.
That is $9,000 a year more than Comprehensive, which stays at $15,000 whichever way the year goes.
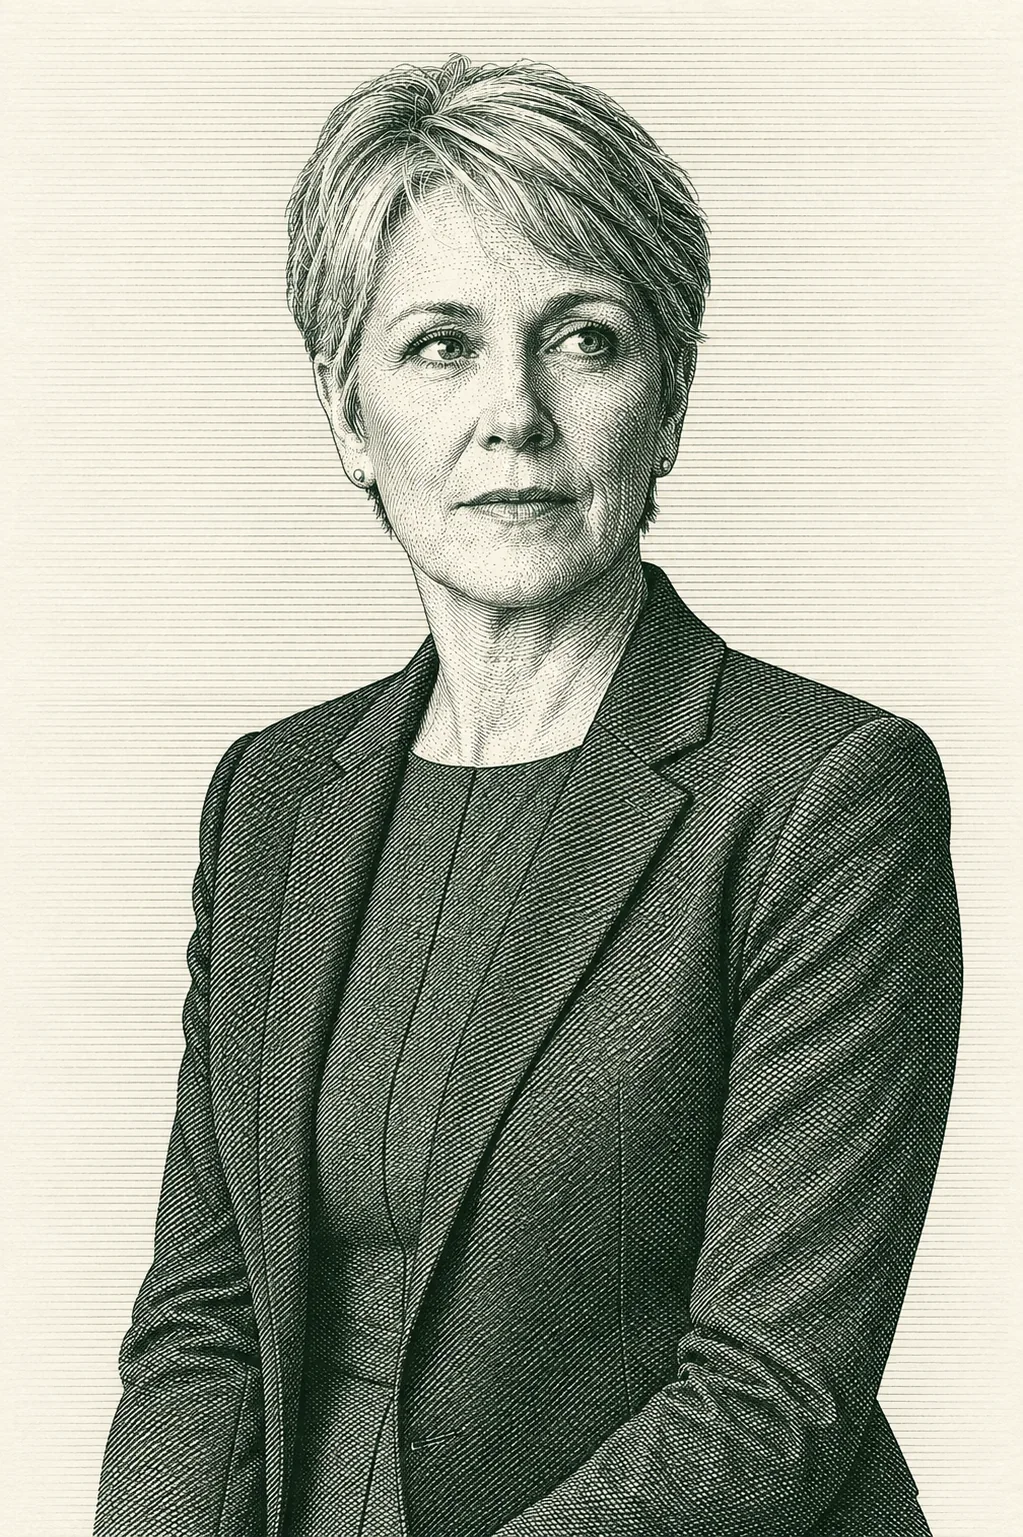
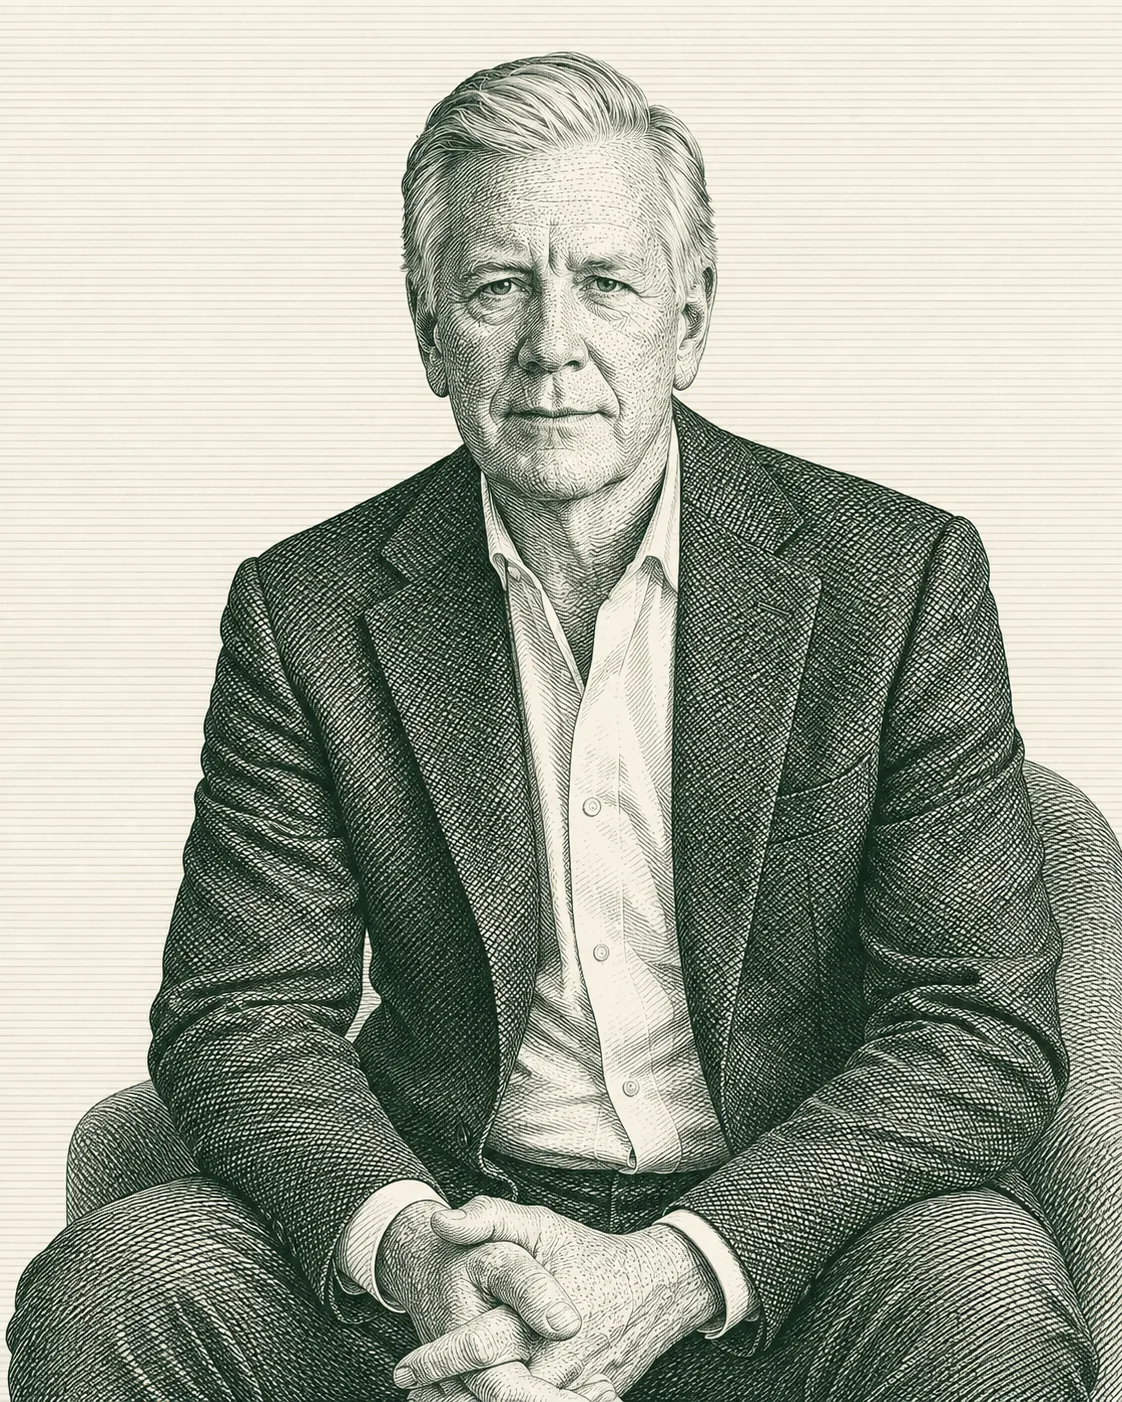
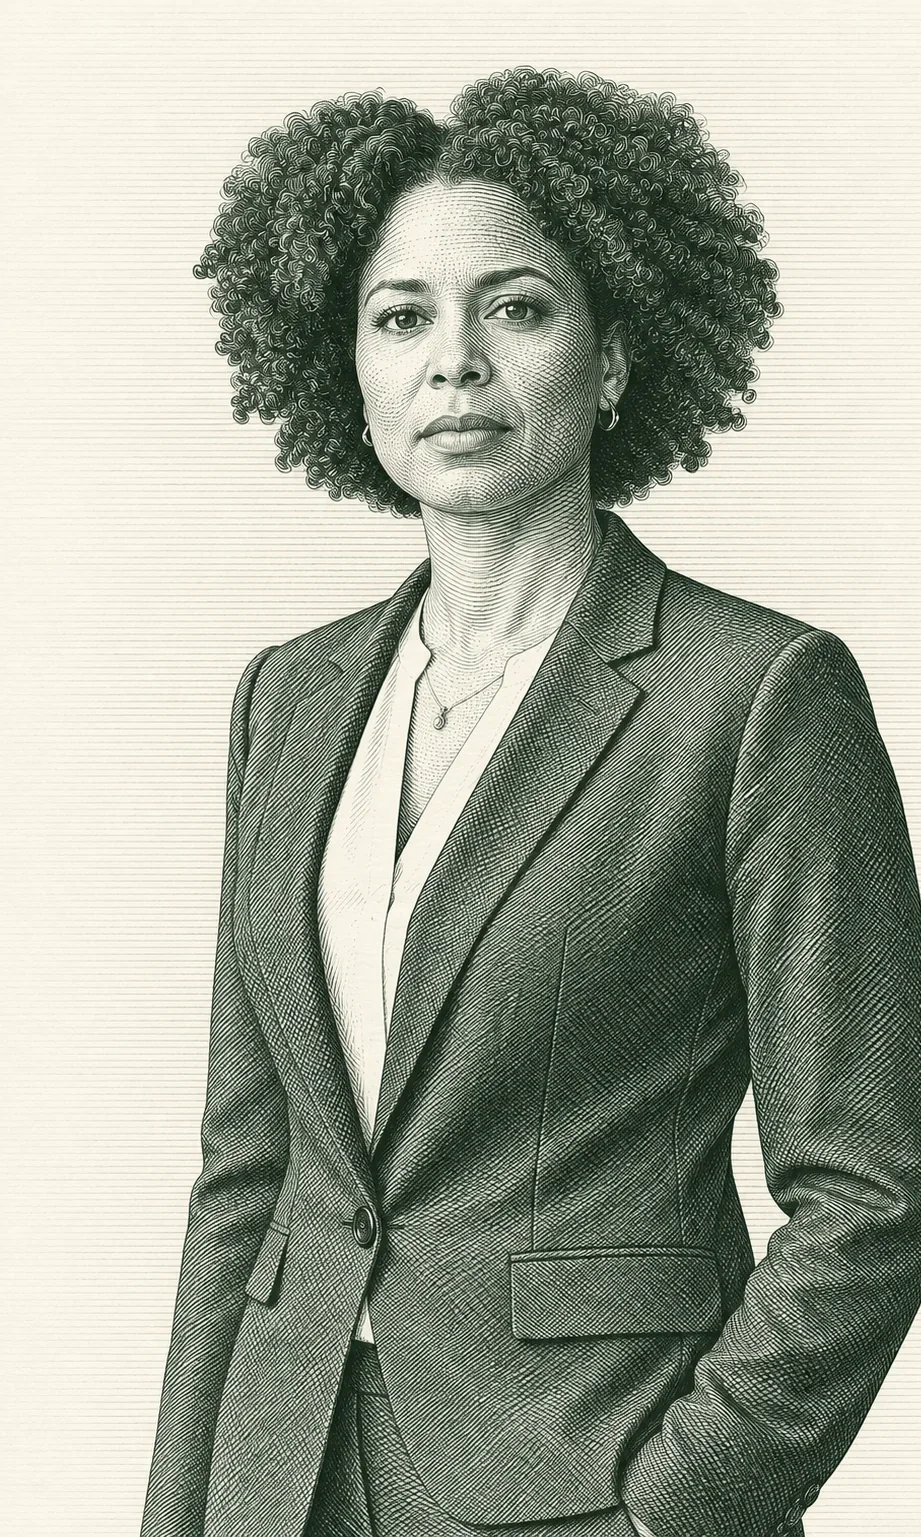
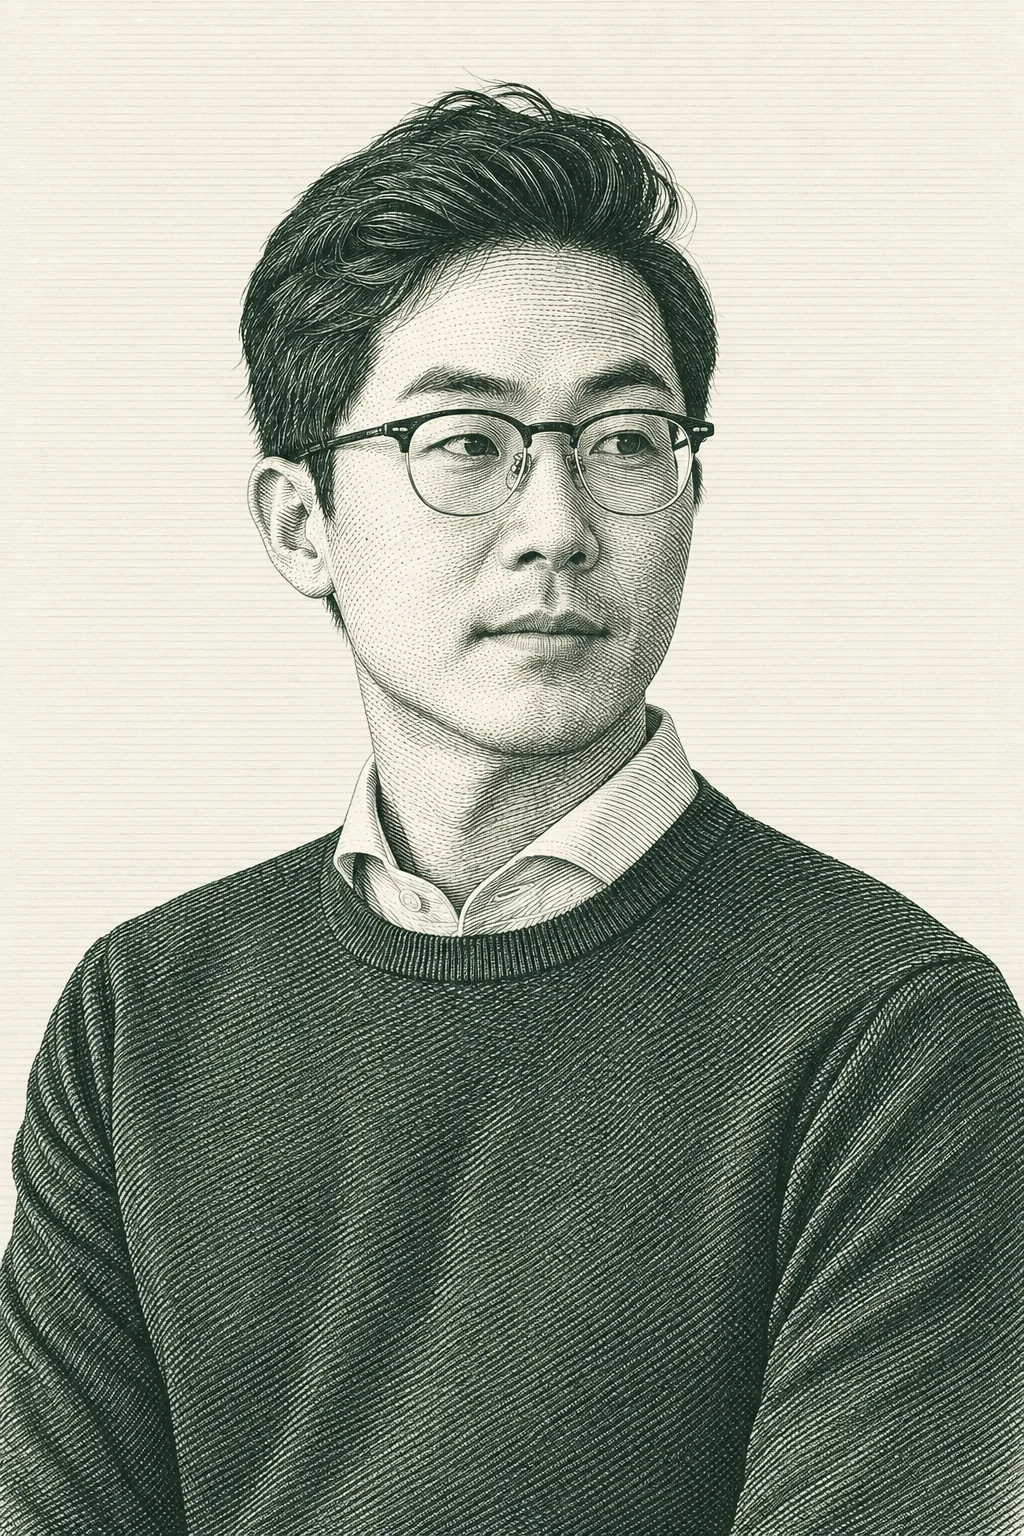
Five advisors. The one who takes your intro call draws your plan.
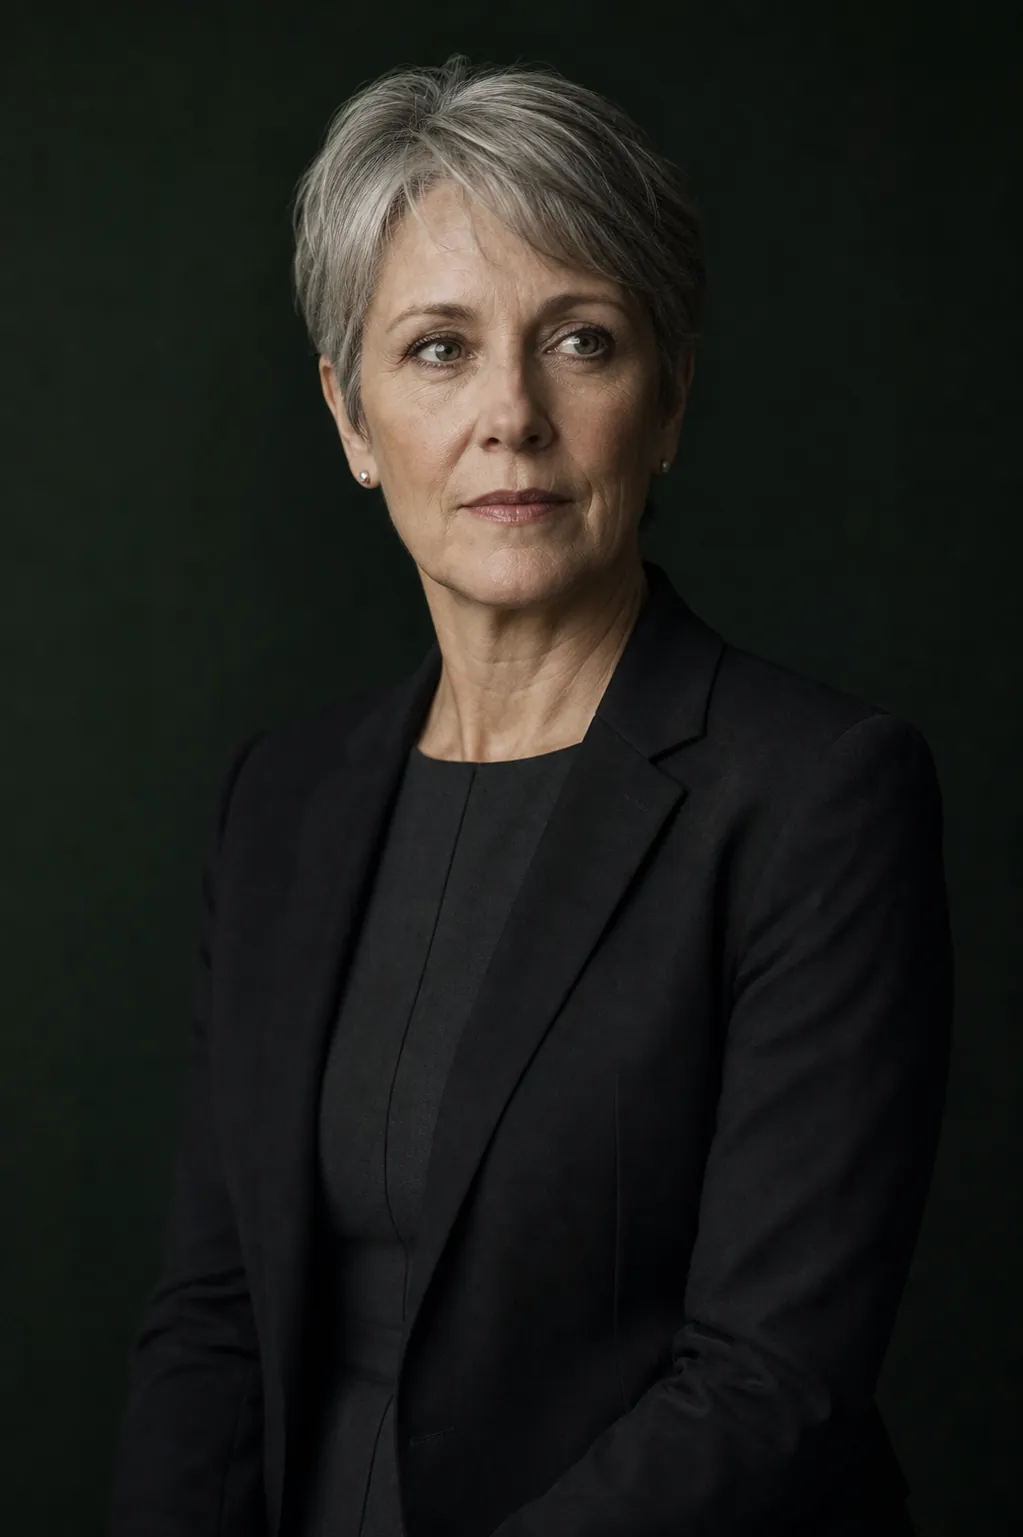
Eleanor Marsh
Founding advisor
Retirement transitions, twenty-four years of them. She draws the first line on every plan that leaves this office.
The advisor who takes your intro call draws your plan, runs the annual redraw, and picks up when the offer letter lands.
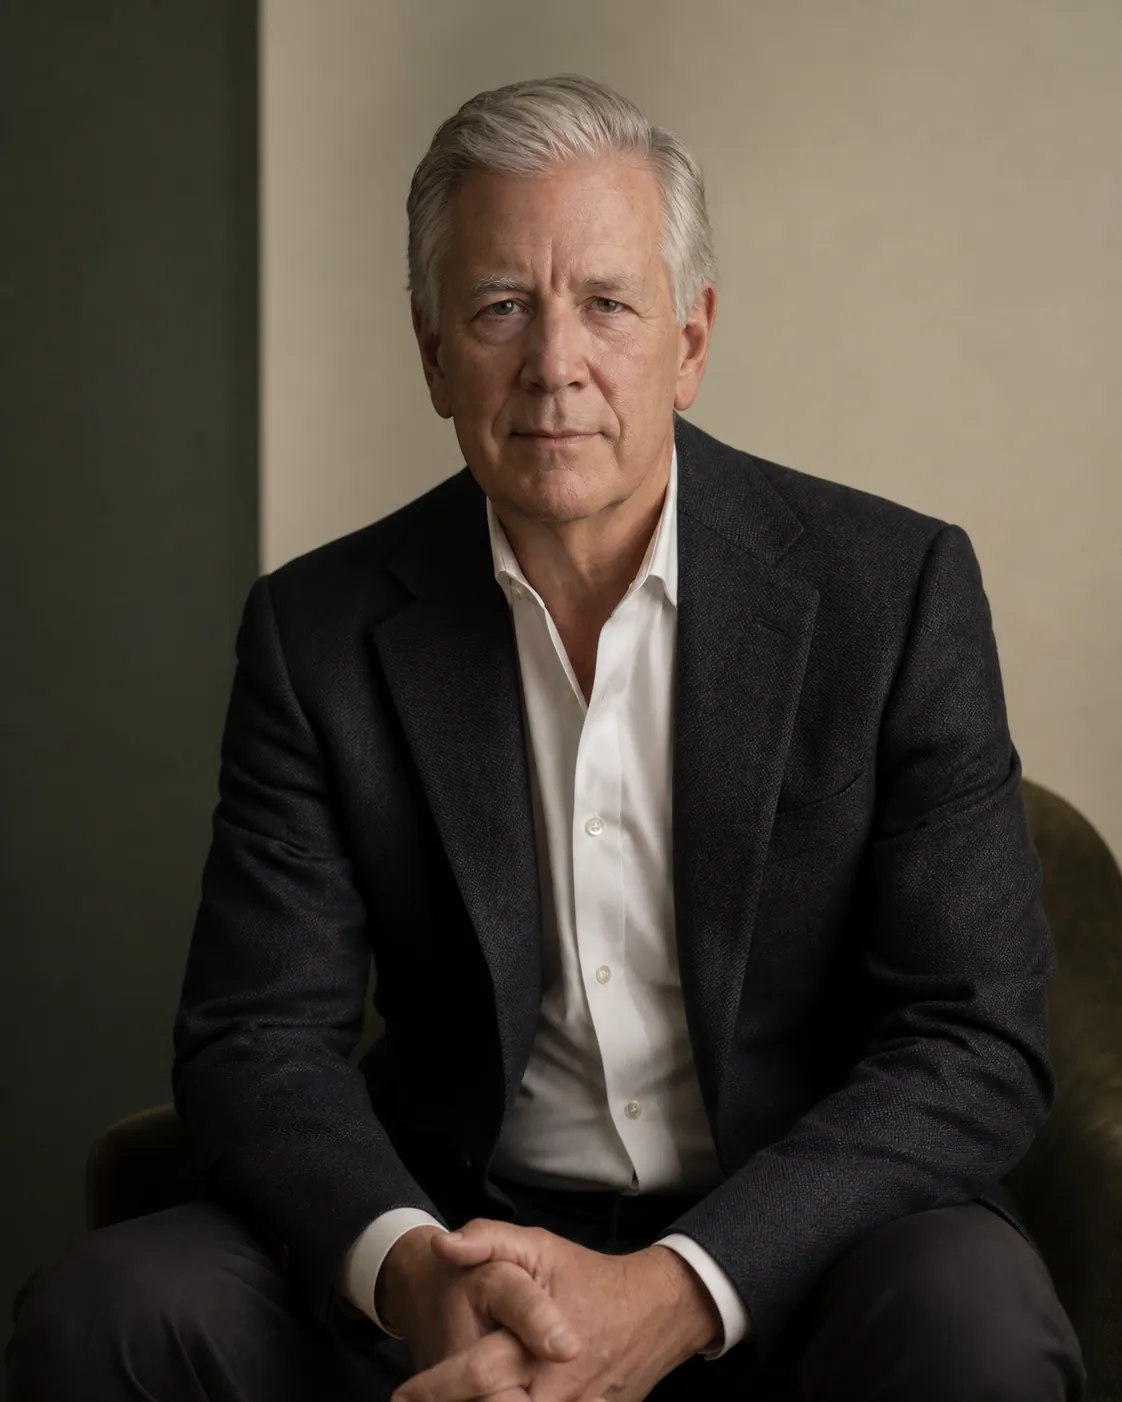
David Okafor
Equity compensation
Options, RSUs, and the grant agreements nobody reads. He reads them, and then he tells you what page nine actually costs.
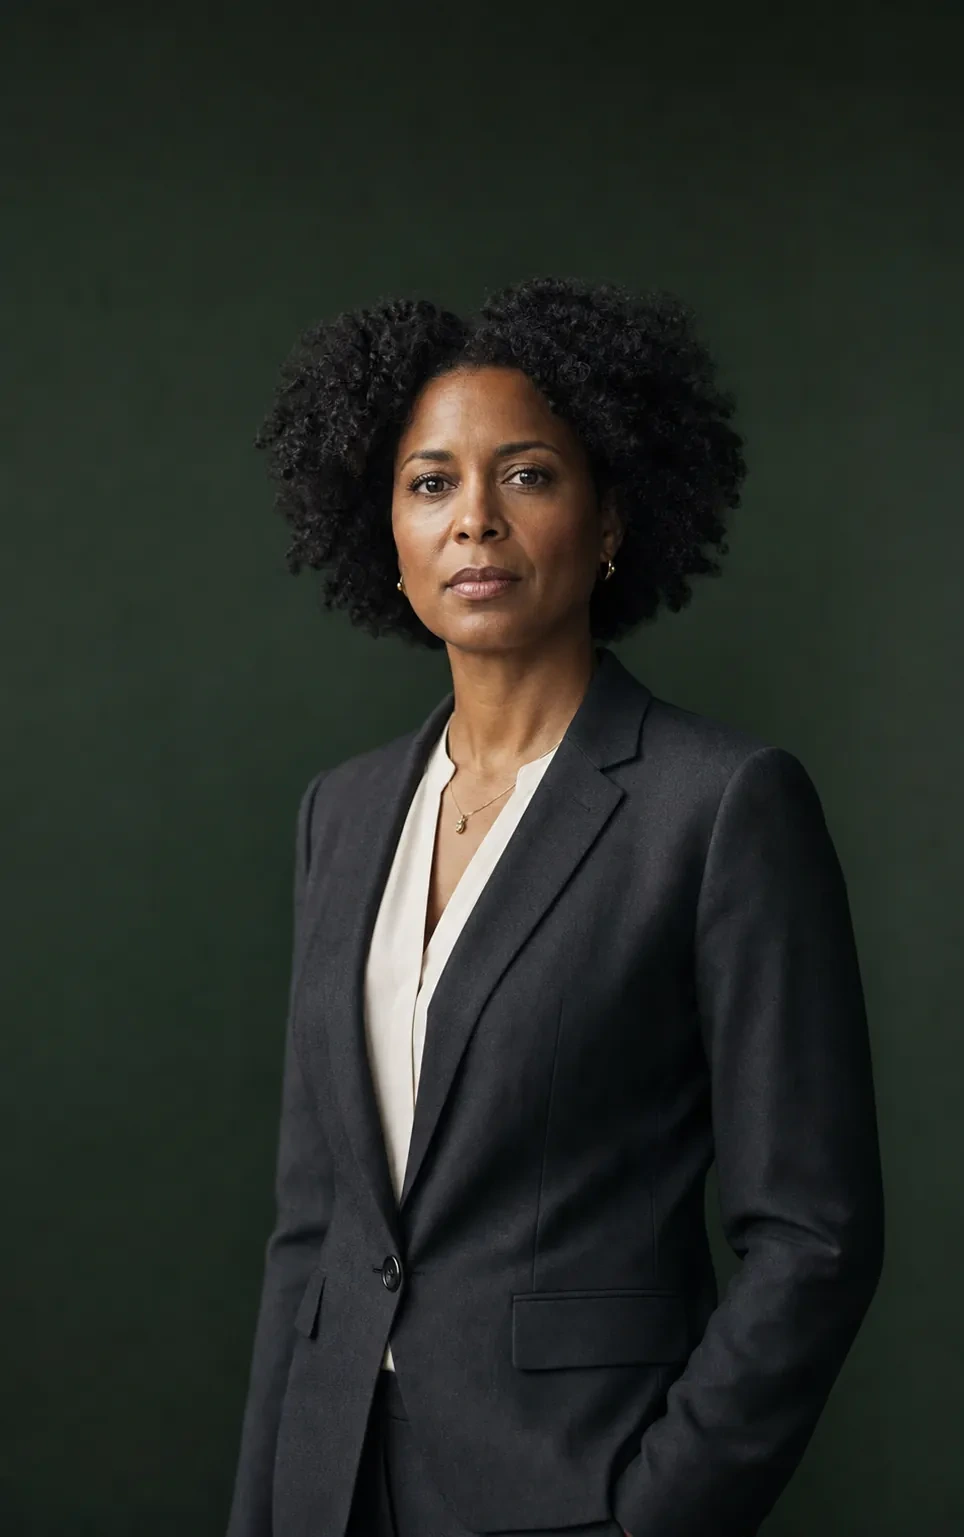
Priya Raman
Tax strategy
The reason the withdrawal order works as well in April as it does on paper. Talks to your CPA so you do not have to.
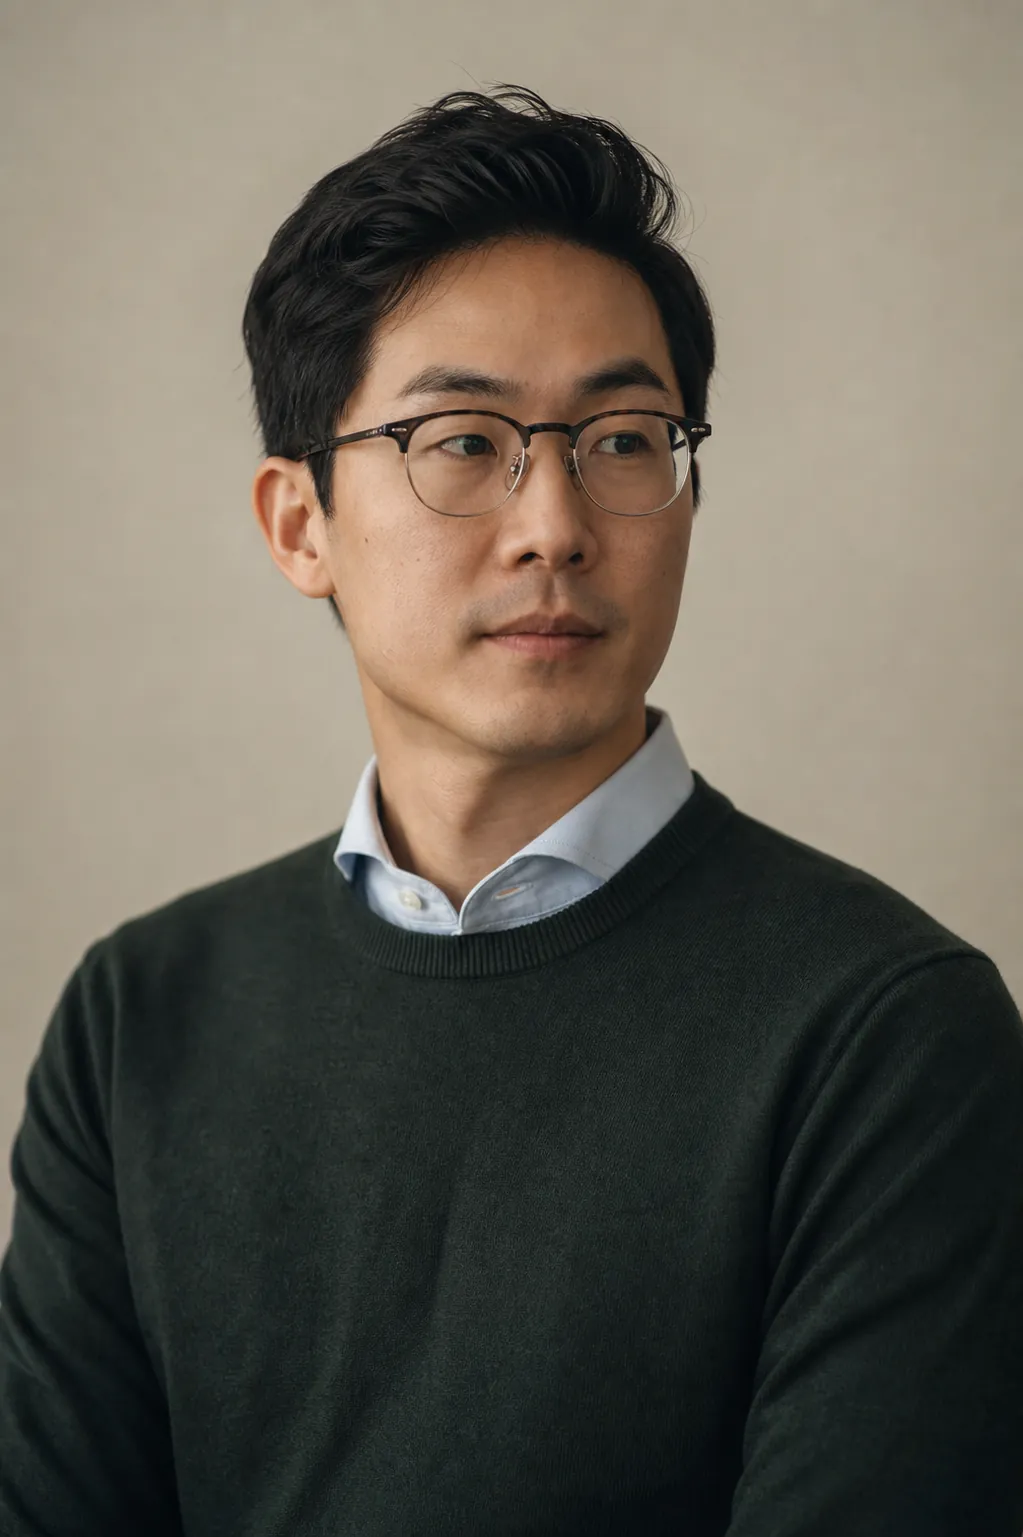
Tom Kessler
Pensions and severance
A former actuary who has likely seen a version of your offer before, and can tell you which number in it is the real one.
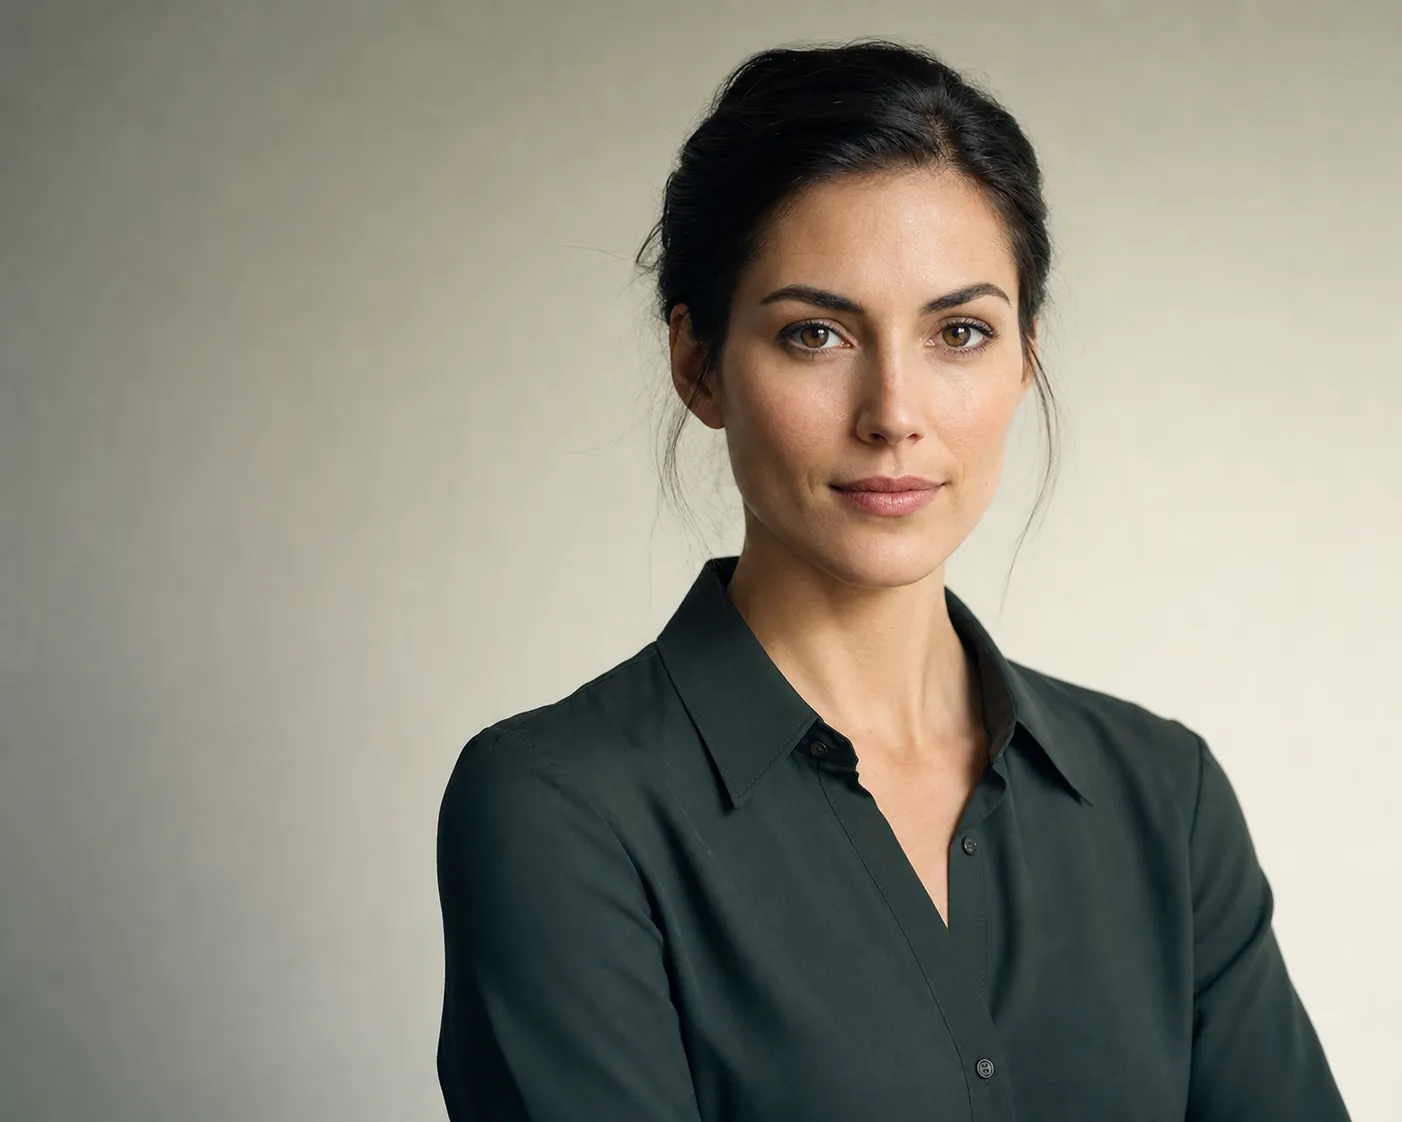
Grace Liu
Concentrated stock
She builds the selling schedule, and the case for keeping some. Both are written down before the first share moves.
Bring us the decision you’ve been circling.
Come with the offer letter, the vesting schedule, or the retirement date you haven’t said out loud yet. In 45 minutes we’ll tell you what we see, what we’d charge, and whether you need us at all. Sometimes the honest answer is a two-hour plan review and nothing more.
No fee is charged for the first call, and none is owed if you walk away from it.